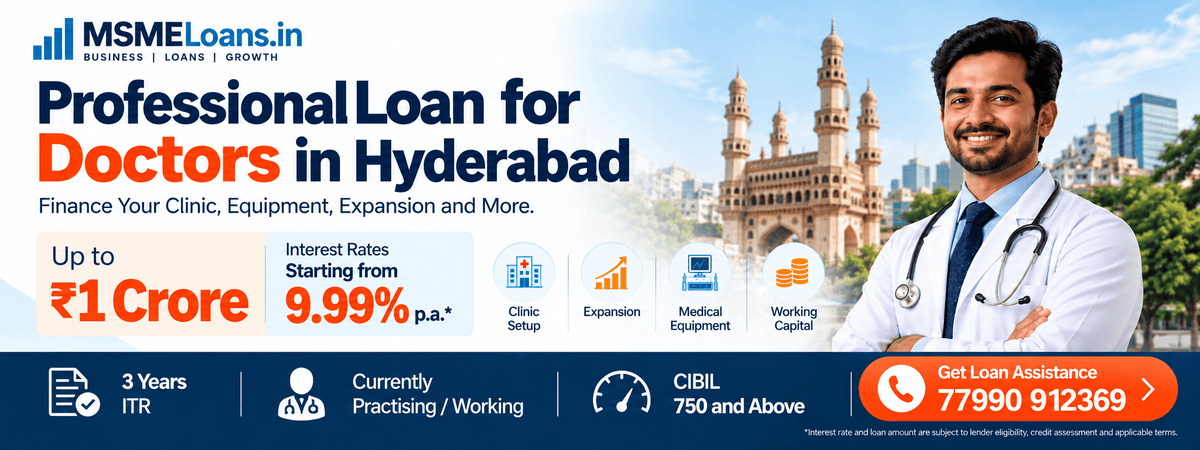
Professional loan for doctors in Hyderabad helps MBBS doctors, specialists, surgeons, dentists and clinic owners fund a new clinic, expansion, medical equipment, interiors and
working capital, often without property as collateral. Depending on income, practice vintage and lender, eligible doctors can look at funding of up to
₹1 crore*. Compare lenders, eligibility, fees and documents below, then share your requirement for free guidance.
Professional Loan for Doctors in Hyderabad: Quick Facts
| Feature |
Typical Terms* |
| Loan amount |
Up to ₹1 crore* for eligible profiles |
| Interest rate |
From 9.99% p.a.*; most lenders start between 11% and 14%, depending on your ITR / income and profile |
| Tenure |
4-5 years; varies by lender and loan type |
| Collateral |
Not required by many lenders for eligible profiles; larger amounts may need security |
| Processing fee |
From around 1% of the loan amount (plus GST); varies by lender |
| Who can apply |
MBBS, MD/MS, dentists, consultants, clinic and hospital owners |
*Indicative. Final terms depend on the lender, credit assessment and your financial profile.
What Is a Professional Loan for Doctors?
A professional loan is a financing facility for qualified professionals such as doctors. Lenders assess your qualification, registration, practice income and credit history, so it is usually available without pledging property. It differs from a personal loan because it is sized around your practice and can be used for business needs.
You can use it for
clinic setup, expansion, interiors, equipment and
working capital. For the full range of options, see our guide to
doctor loans in Hyderabad.
What Can a Doctor Use a Professional Loan For?
- Starting a new clinic in Hyderabad
- Expanding an existing clinic or adding branches
- Buying medical and diagnostic equipment (see machinery loan for MSME)
- Clinic renovation, interiors and operation theatre set-up
- Working capital, hiring staff and inventory
- Opening a diagnostic centre
- Hospital or nursing-home expansion
Professional Loan Eligibility for Doctors
Eligibility varies by bank and NBFC. The table shows what lenders commonly look at.
| Criteria |
Typical Requirement* |
| Qualification |
MBBS / BDS / MD / MS or equivalent recognised degree |
| Registration |
Valid registration (Telangana Medical Council / NMC or relevant council) |
| Age |
As per lender policy |
| Practice experience |
Minimum period set by each lender; MBBS doctors may need more years than PG / specialist doctors |
| Credit score |
A good CIBIL score and clean repayment record are preferred |
| Income proof |
Latest ITRs and recent bank statements |
| Existing loans |
EMIs should be manageable against your income |
Larger loans may also be assessed on clinic turnover, profitability and banking transactions.
MBBS Doctors vs Specialists
Many lenders ask MBBS doctors for more years of practice than PG qualified specialists, because specialist income is typically higher and more stable. A new PG doctor with a strong profile can sometimes qualify earlier. Share your details and we will check which lenders suit your stage of practice.
Professional Loan Interest Rates for Doctors
Rates depend on the lender and your profile. Doctors with a strong credit score, stable income and an established practice may qualify for better terms.
| Lender |
Indicative Interest Rate |
Loan Type |
Best Suited For |
| HDFC Bank |
13.5% |
Professional / Business Loan |
Clinic expansion and professional requirements |
| IDFC FIRST Bank |
From 9.99%* |
Professional / Personal Loan |
Personal and professional requirements |
| Bajaj Finance |
11%–17.50% p.a. |
Doctor Loan |
Practice expansion and medical equipment |
| YES BANK |
Profile-based |
Professional / Business Loan |
Doctors and professional businesses |
| SMFG India Credit |
From 12.5% p.a. |
Doctor Loan / Business Loan |
Personal needs and practice expansion |
Note: Interest rates are indicative and may change. The final rate depends on the lender’s current policy, credit score, income, loan amount, tenure and overall applicant profile. See also our
loan types and interest rates page.
Fees and Charges to Check Before You Sign
| Charge |
What to Check |
| Processing fee |
Percentage of the loan amount, plus GST |
| Foreclosure charges |
Percentage of outstanding principal, and any lock-in period |
| Part-prepayment charges |
Percentage of the amount prepaid |
| Stamp duty / documentation |
As applicable in Telangana |
| Bounce / late payment |
As per the lender’s schedule |
Always compare the
total cost (interest plus fees), not only the headline rate.
EMI Example for a Doctor’s Professional Loan
These are illustrations at an assumed rate of 14% p.a. and are not an offer. Your actual rate may be higher or lower.
| Loan Amount |
Tenure |
Monthly EMI |
Total Interest |
| ₹25 lakh |
5 years |
≈ ₹58,171 |
≈ ₹9.9 lakh |
| ₹50 lakh |
5 years |
≈ ₹1,16,341 |
≈ ₹19.8 lakh |
Documents Required for a Professional Loan for Doctors
Most banks and NBFCs ask for personal, professional, financial and clinic documents. Requirements vary by lender and loan amount.
🪪
Personal Documents
- PAN Card
- Aadhaar Card / valid ID proof
- Address proof
- Recent photograph
🩺
Professional Documents
- Medical degree / qualification certificate
- Telangana Medical Council / NMC registration certificate
- Proof of professional practice
📊
Income & Financial Documents
- Recent bank statements
- Income Tax Returns (ITR)
- Computation of income
- Financial statements
- GST returns, if applicable
🏥
Clinic or Business Documents
- Clinic registration
- Business registration documents
- GST documents, if applicable
- Lease / rental agreement
- Quotations for equipment or interiors
Can Doctors Get a Professional Loan Without Collateral?
Yes. Eligible doctors can get unsecured professional loans from certain banks and NBFCs. The maximum amount without collateral depends on income, credit profile, practice experience and lender policy.
Higher amounts, such as the
up to ₹1 crore* range, usually need a strong income profile, an established practice, a good credit score and a clean repayment record. For larger funding needs, a
loan against property can give a bigger amount and longer tenure. You may also explore
CGTMSE-backed loans for doctors, or check
CGTMSE loans in Hyderabad.
Professional Loan vs Personal Loan vs LAP vs CGTMSE
| Option |
Collateral |
Best For |
| Professional loan |
Usually none |
Clinic set-up, equipment, expansion |
| Personal loan for doctors |
None |
Personal needs, smaller amounts |
| Loan against property |
Residential / commercial property |
Large amounts, long tenure |
| CGTMSE-backed loan |
Collateral-free under the scheme, subject to lender |
Eligible clinics and MSMEs |
Professional Loan for New Clinics in Hyderabad
A new clinic has no turnover history, so lenders lean on your income, experience, credit history and promoter contribution. For larger hospital or healthcare projects, banks may ask for a project report, projected cash flows and collateral. Typical set-up scenarios in Hyderabad include a consulting clinic in Banjara Hills or Jubilee Hills, a dental or skin clinic in Gachibowli or Kondapur, and a diagnostic or day-care set-up in Secunderabad.
Professional Loan for Clinic Expansion
Established practices can use the loan to add equipment, increase capacity, renovate premises or manage working capital. Lenders look at turnover, profitability, banking transactions and repayment history to set the amount and terms.
How to Apply for a Professional Loan in Hyderabad
- Share your requirement: amount, purpose and practice details.
- Profile assessment: we review income, practice vintage, CIBIL score and existing liabilities.
- Lender matching: we shortlist banks and NBFCs that fit your profile.
- Documentation and credit assessment: we help prepare a clean proposal.
- Sanction and disbursal: the lender approves and releases funds.
How MSMELoans.in Can Help Doctors in Hyderabad
MSMELoans.in is a loan facilitation service. We evaluate your requirement, practice income, CIBIL score, liabilities and available security, structure the proposal, and approach suitable banks and NBFCs. The final approval, rate and terms rest with the lender.
Share your loan requirement with us and our team will evaluate the right financing options for your profile.
Check Eligibility Call / WhatsApp +91 77996 12369
Frequently Asked Questions
Can a new MBBS doctor get a professional loan in Hyderabad?
It depends on the lender. Many ask for a minimum period of practice and income proof. Doctors with less experience may need a co-applicant or a different product. Share your profile and we will check suitable options.
What CIBIL score is needed for a doctor’s professional loan?
Requirements vary by lender. A higher score generally gets better rates and approval chances. We can tell you which lenders suit your score.
Is collateral required for a professional loan for doctors?
Many lenders offer unsecured professional loans to eligible doctors. Larger amounts may need security, depending on the lender and your profile.
Can dentists apply for a professional loan?
Yes. Dentists and other qualified medical practitioners are commonly eligible, subject to each lender’s policy. See our page on
dental clinic loans.
Can I use a professional loan to buy medical equipment?
Yes. Equipment purchase is one of the most common uses, along with clinic set-up, interiors and working capital.
Can I prepay or foreclose a professional loan?
Most lenders allow it, but part-prepayment and foreclosure charges differ. Check the lender’s schedule before you sign.
MSMELoans.in is not a bank or NBFC. We facilitate loans by connecting borrowers with banks and financial institutions. Loan approval, interest rates, tenure and eligibility are at the lender’s discretion. We do not guarantee approval. *Indicative figures; see lender terms.