Running a clinic, hospital or diagnostic centre? Our guide to the MSME loan for doctors explains collateral-free CGTMSE funding and business loans in detail.
Last updated: 11 October 2026 | Written by [Raja Venkat loan & Insurance Advisor] ]
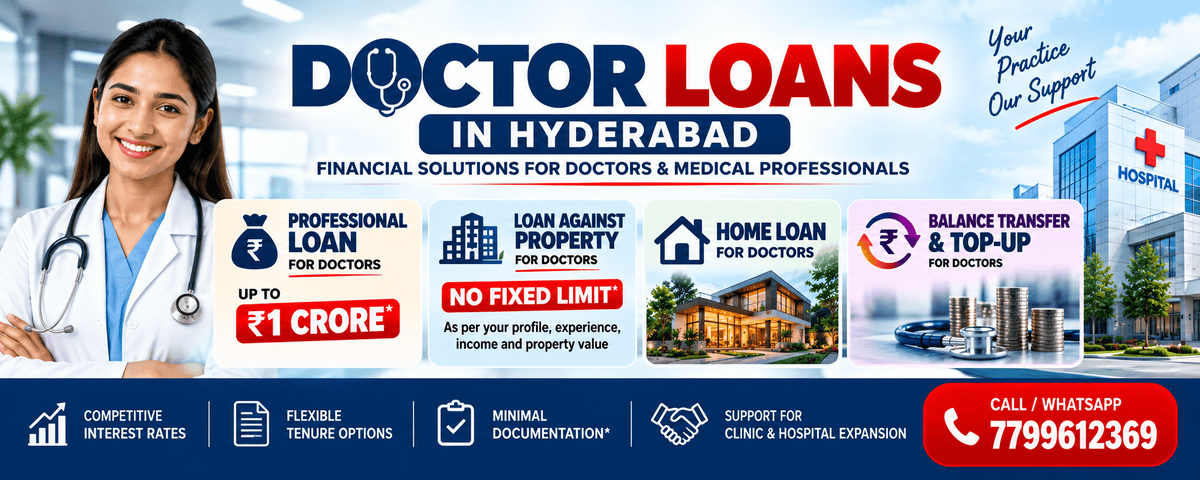
Doctor Loans in Hyderabad at a Glance
| Loan type | Typical amount | Collateral | Best for |
|---|---|---|---|
| Professional loan | Up to ₹1 crore (lender-dependent) | Usually none | New or small clinic, equipment, working capital |
| MSME business loan (CGTMSE) | Up to ₹10 crore | Often none up to about ₹1–3 crore | Clinic setup, hospital, diagnostic centre expansion, Medical Equipment purchase |
| Loan against property | Based on property value | Property | Large funding, lower rates |
| Home loan | Based on income and property | Property being bought | Residence purchase or construction |
| Balance transfer / top-up | Outstanding loan plus top-up | As per existing loan | Lower EMI or extra funds |
Eligibility Criteria for Doctor Loans in Hyderabad
Each lender sets its own rules, but these are the points most lenders check:
- Qualification and registration: MBBS, MD/MS, BDS/MDS, BAMS, BHMS or equivalent, with valid registration from the relevant state or national medical or dental council.
- Age: commonly between the mid-20s and mid-60s at the time of application. Limits vary by lender and product.
- Practice vintage: many professional loans prefer 1–3 years of practice or post-qualification experience. New clinics may qualify with a strong project report, but may need security.
- Income and ITR: filed income-tax returns for the last 1–3 years and consistent bank credits.
- Credit score: a CIBIL score of 700 or above is usually preferred, and many lenders offer their best rates at 750+.
- Existing obligations: existing EMIs and credit card dues affect how much you can borrow.
- Business structure: proprietorship, partnership, LLP or private limited company. Business loans also usually need Udyam Registration.
Tip: before applying, check your credit report, clear overdue dues and route clinic receipts through your bank account. This improves the profile lenders see.
Interest Rates, Tenure and Charges for Doctor Loans
Rates and terms depend on the lender, loan type, your credit profile and whether property is offered as security. The ranges below are indicative and not offers.
| Loan type | Indicative rate | Typical tenure | Notes |
|---|---|---|---|
| Professional loan for doctos | Approx. 9.99% – 17% p.a. | Up to about 5–7 years | Unsecured; rate rises for lower credit scores |
| MSME business loan for doctor | Approx. 9% – 15% p.a. | Up to 10 years | Moratorium of 6–12 months possible for new setups |
| Loan against property | Generally lower than unsecured loans | Often up to 15 years or more | Subject to property valuation and LTV |
| Home loan for Doctors | starts from 7.25% | Up to about 20–30 years | Professional income is assessed on ITR and banking |
Other charges to ask about: processing fee, valuation and legal charges (for property loans), CGTMSE annual guarantee fee (for guaranteed loans), prepayment or foreclosure charges and insurance.
Sample EMI Calculations (Illustrative)
| Loan | Rate | Tenure | Approx. EMI | Total interest |
|---|---|---|---|---|
| ₹25 lakh professional loan | 12% | 5 years | ₹55,600 | ₹8.4 lakh |
| ₹50 lakh clinic and equipment loan | 11% | 10 years | ₹68,900 | ₹32.7 lakh |
Examples are for understanding only. Your sanction letter will state the actual rate, EMI and charges. For smaller or larger amounts, see our guides to the ₹50 lakh MSME loan and the ₹1 crore MSME loan.
Rates in this table were last checked on [date]. Lender names are shown for comparison only. Policies change often, so always confirm current terms with the lender.
Areas We Serve in Hyderabad and Secunderabad
We help doctors across the twin cities. Here are some of the areas where clinics, specialty practices and diagnostic centres commonly operate:
| Area | Common practice types |
|---|---|
| Banjara Hills and Jubilee Hills | Multi-speciality clinics, cosmetic and dermatology practices, premium diagnostics |
| Gachibowli, Kondapur and Madhapur | Family clinics, dental and wellness clinics serving the IT corridor |
| Secunderabad, Begumpet and Marredpally | Nursing homes, consultant clinics, diagnostic labs |
| Kukatpally and KPHB | General practice, dental, paediatric and maternity clinics |
| LB Nagar, Dilsukhnagar and Uppal | Neighbourhood clinics, diagnostic centres, small hospitals |
[Delete any area you do not actively serve, and add others you do.]
Registrations and Approvals a Hyderabad Clinic May Need
Lenders usually ask to see that your practice is properly registered. Depending on the type and size of your facility, this can include:
- Registration of the doctor with the relevant medical or dental council
- Registration of the clinic or hospital under Telangana’s clinical establishment rules
- Trade licence from the municipal authority (GHMC or the local body)
- Bio-medical waste authorisation from the state pollution control board
- Fire safety clearance for hospitals and larger facilities
- Radiation or imaging approvals for X-ray and scan centres
- Udyam Registration for MSME business loans
Requirements change, so confirm the current list with the relevant authority before you apply. [Verify each item against official Telangana sources before publishing.]
Doctor Loan Examples: How Different Doctors Can Structure Funding
Illustrative examples. These show how a loan can be structured. They are not client testimonials, and actual terms depend on the lender.
Example 1: A new dental clinic in a Hyderabad IT corridor
- Need: ₹35 lakh for interiors, two dental chairs and an X-ray unit
- Structure: professional or MSME term loan with a 6-month moratorium, repaid over 7 years
- What the lender looks at: qualification, council registration, project report, equipment quotations, the doctor’s credit score
Example 2: An established specialist expanding a clinic
- Need: ₹1.2 crore to add a procedure room and imaging equipment
- Structure: MSME business loan with CGTMSE cover where the lender allows it, or a hybrid structure that pledges part of the exposure
- What the lender looks at: 3 years of ITR, TDS, bank statements showing steady receipts and AAB average account balance , DSCR from the projected revenue
Example 3: A hospital owner who needs larger funding
- Need: ₹4 crore for a new floor and ICU equipment
- Structure: secured term loan against the hospital property, with a loan against property as an alternative
- What the lender looks at: property valuation, legal title, hospital turnover and approvals
What CIBIL score is needed for a doctor loan in Hyderabad?
Most lenders prefer 700 or above, and the best on intrest rates usually go to scores of 750 and higher. A lower score may still get approval, but with a higher rate or a need for security.
Can a new doctor with no ITR get a loan?
It is harder. Lenders rely on ITR and bank statements to judge repayment capacity. Doctors starting out may still qualify with a strong project report, a co-applicant income or property as security.
How much does it cost to set up a clinic in Hyderabad?
The cost depends on the speciality, location, premises size and equipment. A basic consulting clinic costs far less than a dental, imaging or day-care facility. Prepare itemised quotations for interiors and equipment, because lenders size the loan from them.
Which documents does a Hyderabad clinic loan need beyond KYC?
Medical council registration, clinic registration and trade licence, Udyam Registration for business loans, ITR, bank statements, a project report and equipment quotations. Property loans also need title and valuation documents.
How long does a doctor loan take to get approved?
It depends on the lender, the loan type and how complete your documents are. Unsecured professional loans are generally quicker than loans that need property valuation and legal checks.
Is a loan available for a clinic in Banjara Hills, Gachibowli or Secunderabad?
Yes. Location does not decide eligibility on its own, but lenders look at premises ownership or lease terms, expected patient flow and your documents. Premium locations usually have higher rent and fit-out costs, which affects the loan size.
Should I choose a professional loan, an MSME loan or a loan against property?
For smaller funding without security, a professional loan is usually quicker. For clinic or hospital projects with equipment, a business loan with CGTMSE cover can suit better. For large amounts and lower rates, a loan against property is worth comparing. See our MSME loan for doctors guide to compare.
Can women doctors get any extra benefit?
CGTMSE offers higher guarantee cover and a fee concession for women-led enterprises. See our page on CGTMSE loans for women.
Apply for Doctor Loans in Hyderabad
Tell us your requirement, whether a clinic, hospital, equipment, property purchase or an existing loan transfer. We will review your profile and discuss suitable loan structures with lenders.
Call +91 77996 12369 | WhatsApp | Apply for doctor loan assistance
Hours: Monday to Saturday, 10:00 AM – 7:00 PM
MSMELoans.in is a loan facilitation service and not a bank or NBFC. Loan amount, interest rate, tenure and approval are decided by the lender, and subject to documentation, credit assessment and, where relevant, property evaluation. We do not guarantee approval.